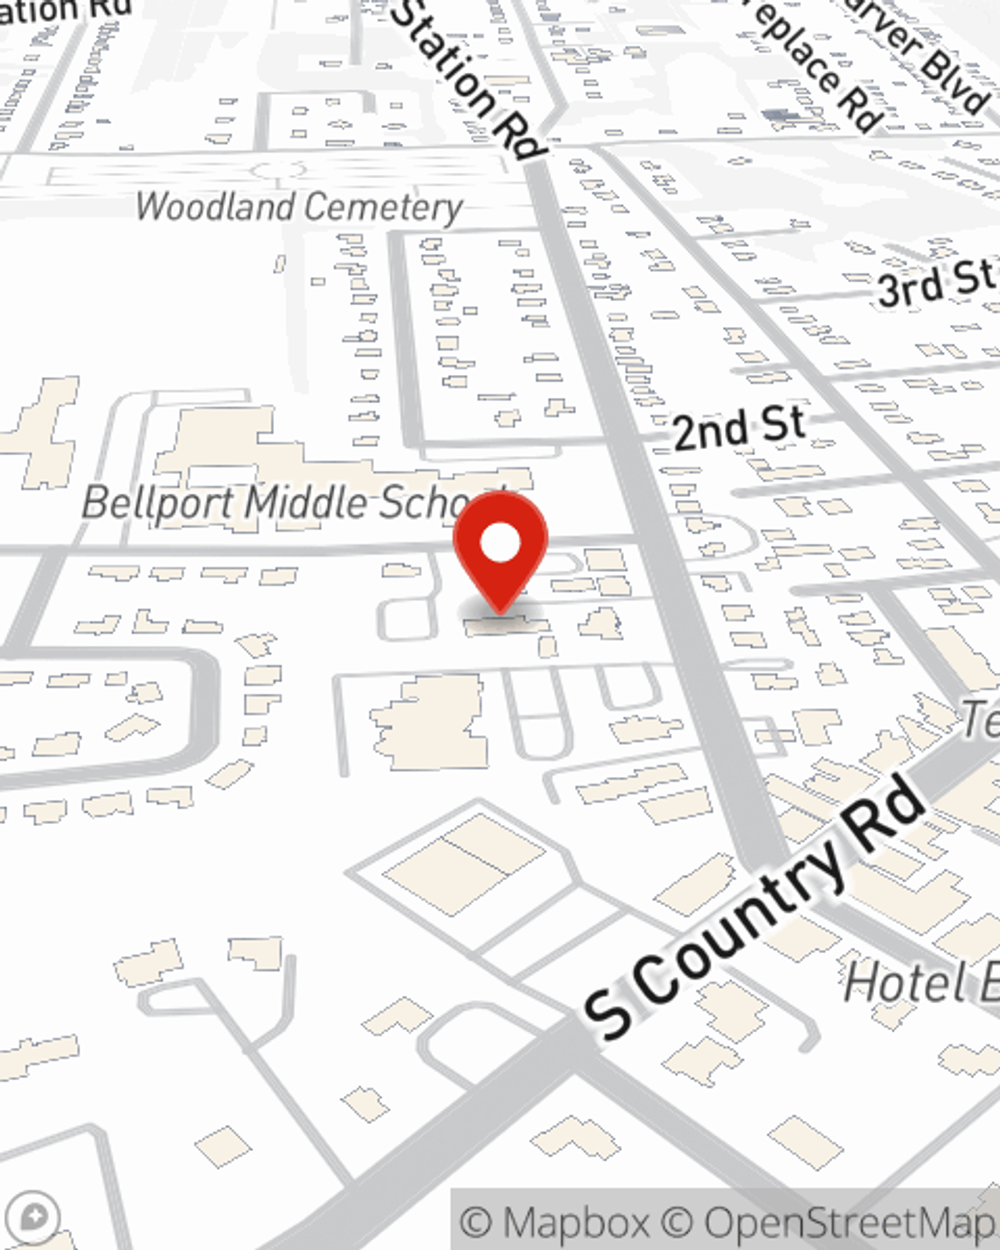
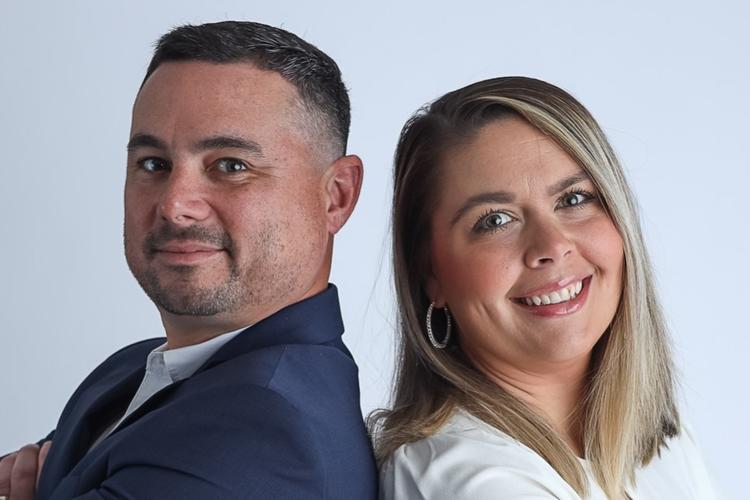
I’m Gregory Mehrhoff, ChFC®, a State Farm Agent in Bellport, New York, serving individuals, families and businesses throughout Long Island and across New York.
My approach to insurance is straightforward: understand the household first, then talk about the insurance. A good insurance conversation should go beyond simply finding a price. We take the time to understand what you own, who depends on you, what has changed in your life, and where there may be gaps or opportunities within your current coverage.
My team can help with Auto Insurance, Homeowners Insurance, Renters and Condo Insurance, Life Insurance, Business Insurance, Personal Articles coverage and other State Farm insurance products. We also regularly help customers review how their policies work together so they can understand their coverage and the discounts that may be available when multiple policies are combined.
As a ChFC®, I also bring a broader financial perspective to customer conversations. Insurance is an important part of protecting your plan, and life events such as buying a home, getting married, having children, changing jobs or preparing for retirement can all be good reasons to review both your insurance and your longer-term financial goals.
Our agency believes the relationship shouldn't end when a policy is issued. New customers receive onboarding and we encourage ongoing policy reviews as their household changes. Whether you've been with State Farm for years or you're comparing State Farm with your current insurance company, our goal is to help you understand your options and make an informed decision.
We're based in Bellport, NY and serve customers throughout Suffolk County and Long Island, including customers looking for help with their Auto, Home and Life insurance needs. Our agency is also licensed to assist customers in additional states where appropriate.
If you're shopping for insurance, have questions about your current coverage, or simply haven't reviewed your policies in a while, give our office a call or schedule a conversation with our team. We're happy to help you take a fresh look.
Gregory Mehrhoff, ChFC® State Farm Agent Bellport, New York
Greg Mehrhoff State Farm — Long Island Insurance FAQ
October 2026
How much Auto insurance coverage should I have in New York?
There isn't one liability limit that's right for every New York driver. The amount of Auto insurance you should carry depends on more than the value of your vehicle. Your income, assets, household members, driving habits, other vehicles and overall financial situation can all affect how much liability protection makes sense.
One of the most important distinctions is between insurance that satisfies New York's legal requirements and insurance designed to protect your household from a significant financial loss. Those aren't necessarily the same thing.
When we review Auto insurance with customers at the Greg Mehrhoff State Farm Agency in Bellport, NY, we look beyond the question of “What's the cheapest policy?” We discuss bodily injury and property damage liability, uninsured/underinsured motorist protection, deductibles, physical-damage coverage, rental reimbursement and other applicable coverage and discount options.
For households with significant assets or liability exposure, it can also be appropriate to discuss whether a Personal Liability Umbrella Policy should be considered.
The goal isn't simply to carry more insurance. It's to understand what you're protecting and what financial risk you're comfortable retaining yourself.
Why did my Auto insurance go up even though I didn't have an accident?
This is one of the most common questions we hear from customers on Long Island.
Your individual driving history matters, but it isn't the only factor affecting an Auto insurance rate. Insurance rates reflect the cost of the risks being insured, which can include changes in repair costs, vehicle technology, medical costs, claim frequency and severity, where and how a vehicle is used, household drivers, mileage, available discounts and other rating factors permitted by the applicable insurance program.
That means a customer can sometimes experience a rate increase even without personally having an accident.
The better question isn't only “Why did my price go up?” It is also “Is my policy still structured appropriately?”
A renewal can be a useful time to review drivers, vehicles, annual mileage, deductibles, available discounts and other policies in the household. We don't recommend removing important protection simply to produce a lower number. We first want to understand what changed and then determine what reasonable options are available.
Should I bundle my Home and Auto insurance?
Bundling can be worth evaluating, but it shouldn't be assumed to be the right answer without looking at the entire household.
Combining Auto and Homeowners insurance with the same company may create multiline discounts. The important calculation, however, is the total household insurance cost and coverage, not merely the discount percentage displayed on one policy.
For example, moving a Homeowners policy could potentially affect the Auto Rate because of an additional multiline discount. That's why we often calculate the proposed Home Rate and the resulting change to the Auto Rate before comparing the new arrangement with what the customer currently pays.
We also compare coverage. Saving money isn't particularly useful if the new Homeowners policy leaves the customer with materially different protection they don't understand.
At our Bellport agency, we try to answer the practical question:
“If I move another policy, what will my household actually pay and what coverage will I have?”
How much dwelling coverage should I have on my Long Island home?
Your dwelling coverage shouldn't automatically be based on your home's market value, purchase price or balance of your Mtg.
Homeowners insurance generally needs to consider the estimated cost to rebuild the structure after a covered loss. The cost of reconstructing a home can be very different from what that home would sell for because land value, construction labor, materials, debris removal, building characteristics and other factors affect the numbers differently.
That's why we spend time reviewing the information used in the home's estimated replacement cost.
Customers should tell us about significant features and improvements—finished basements, additions, upgraded kitchens, bathrooms and other changes—because inaccurate property information can affect the replacement-cost estimate.
The objective is to have an informed conversation about what it could take to rebuild the home rather than simply choosing an arbitrary coverage number.
Does Homeowners insurance cover water backing up through a sewer or drain?
A standard Homeowners policy should not simply be assumed to cover every type of water loss.
Damage involving water backing up through a sewer or drain can be treated differently from other types of covered water damage, and applicable coverage may require a specific endorsement with its own limit and terms.
This is particularly important because people often use the word “flooding” to describe very different events. Water entering from outside surface conditions, a plumbing loss inside the house, and a sewer or drain backup are not necessarily treated the same way under an insurance policy.
When reviewing Homeowners coverage, ask specifically:
“What happens if water backs up through my sewer or drain, and how much coverage do I have?”
Don't wait until there's water in the basement to find out.
Should I keep Comprehensive and Collision coverage on an older car?
Age alone doesn't determine the answer.
The better question is whether you could comfortably absorb the financial loss if the vehicle were damaged or totaled.
Consider the vehicle's current value, your deductibles, the cost of the physical-damage coverage, whether there's a loan or lease, your financial ability to replace the vehicle, and how dependent you are on it.
For some inexpensive older vehicles, assuming more of that risk personally may eventually make sense. For another household, losing even an older vehicle unexpectedly could create a significant financial problem.
This is why we prefer discussing the tradeoff instead of automatically saying, “The car is old, drop Comprehensive and Collision.”
Does Auto insurance provide me with a rental car if my car simply breaks down?
Generally, rental reimbursement coverage associated with an Auto insurance policy is intended for a covered loss—not ordinary mechanical failure.
This distinction surprises some customers.
If your insured vehicle is involved in a covered accident or other qualifying covered loss and your policy includes applicable rental reimbursement coverage, rental expenses may be covered subject to the policy's terms and limits.
If the engine simply fails, the transmission breaks or the vehicle otherwise becomes unusable because of an ordinary mechanical problem, you shouldn't assume your Auto insurance rental coverage will pay for a rental vehicle.
This is a good example of why understanding what triggers coverage can be just as important as knowing that a coverage appears on the declarations page.
What is the difference between replacement cost and market value on a house?
They're measuring different things.
Market value generally relates to what the property might sell for. That includes the value of the land, location and market conditions.
Replacement cost is concerned with what it may cost to reconstruct the insured structure following a covered loss, subject to the policy's provisions.
A Long Island house could therefore have a market value substantially above or below its estimated reconstruction cost.
When reviewing Homeowners insurance, don't simply say:
“My house is worth $700,000, so I need $700,000 of dwelling coverage.”
Instead, review the characteristics of the structure and the replacement-cost estimate used for the insurance policy.
Do I need Life insurance if I already have Life insurance through my employer?
Employer-provided Life insurance can be an important benefit, but it doesn't automatically answer whether your household has enough Life insurance.
Ask several questions:
How much coverage do I actually have? Does it continue if I leave or lose my job? What financial obligations would remain if I died? Who depends on my income? How long would they need support?
Someone changing jobs, getting married, having a child, buying a house or approaching retirement may have very different Life insurance needs than they did several years earlier.
Rather than immediately starting with a product, we prefer starting with the financial obligation. Once we understand what the household would need to accomplish, we can have a more useful conversation about existing coverage and potential gaps.
Why should I review my insurance every year if nothing has changed?
Sometimes the answer after a review really is: nothing needs to change.
That's still useful.
But households evolve gradually, and people don't always think of those changes as insurance events.
A child starts driving. Someone changes jobs. A basement gets finished. You buy jewelry. Your commute changes. You start working from home. You buy a boat. You retire. A mortgage gets paid down. Someone moves into or out of the household.
Individually, those may not cause someone to call their insurance agent immediately.
Over several years, however, the household described on the insurance policies can become very different from the household that actually exists.
A periodic review gives us an opportunity to make sure we're still talking about the same family, property, vehicles and financial situation.
What should I bring to an insurance review?
You don't need to turn an insurance review into a major project.
Start with your current policies and think about what's changed.
Useful information can include current Auto and Homeowners declarations pages, information about drivers and vehicles, approximate annual mileage, significant home improvements, other properties, valuable personal property, Life insurance through work or elsewhere, and major household changes.
We also want to hear about life, not just policies.
Marriage, divorce, children, retirement, job changes, business ownership, a new home, an inheritance or other significant events can create insurance and financial questions that aren't obvious from a declarations page.
The purpose of the conversation is to understand the household first.
Can one insurance agency help me if I own property in more than one state?
Potentially, depending on where the agency and its representatives are appropriately licensed and authorized and whether the applicable products are available.
This can matter for Long Island customers who also own a second home, investment property or other property outside New York.
Having one agency relationship can make it easier to discuss the household as a whole, but insurance remains state-specific. Coverage, eligibility, underwriting requirements and available products can differ by state.
Our agency can determine whether we're able to assist with the particular state and insurance need rather than assuming that a New York policy or process simply transfers elsewhere.
When should I call my insurance agent instead of waiting until renewal?
You don't have to wait for renewal.
Some of the best times to contact your insurance agency are when something meaningful changes:
You're buying a vehicle. You're moving or buying a home. A teenager is getting licensed. You're getting married. You're having a child. You're changing jobs. You're starting a business. You're renovating your home. You're buying expensive personal property. You're approaching retirement.
Those conversations don't automatically mean you need another insurance policy.
They mean something changed, and it's worth determining whether that change affects your existing insurance or financial planning.
What makes the Greg Mehrhoff State Farm Agency's approach different?
We try to understand the household rather than treating each policy as an isolated transaction.
That means asking questions about family, occupation, recreation and money when those subjects are relevant to the conversation. It means onboarding new customers, periodically reviewing existing relationships and looking at how Auto, Home, Life and other insurance needs fit together.
Gregory Mehrhoff is a ChFC®, which also brings a broader financial perspective to conversations where appropriate.
Our agency is located in Bellport, New York, and works with customers throughout Long Island and other areas where we are appropriately licensed and authorized.
The objective isn't to sell something every time we talk.
It's to know enough about the customer that when something does need attention, we can recognize it.